Client Portal
Hartford, Connecticut

Investment Property Loans in Hartford, CT

DSCR loans, plus fix and flip and ground-up construction financing, for investors buying or refinancing in Hartford and surrounding cities.

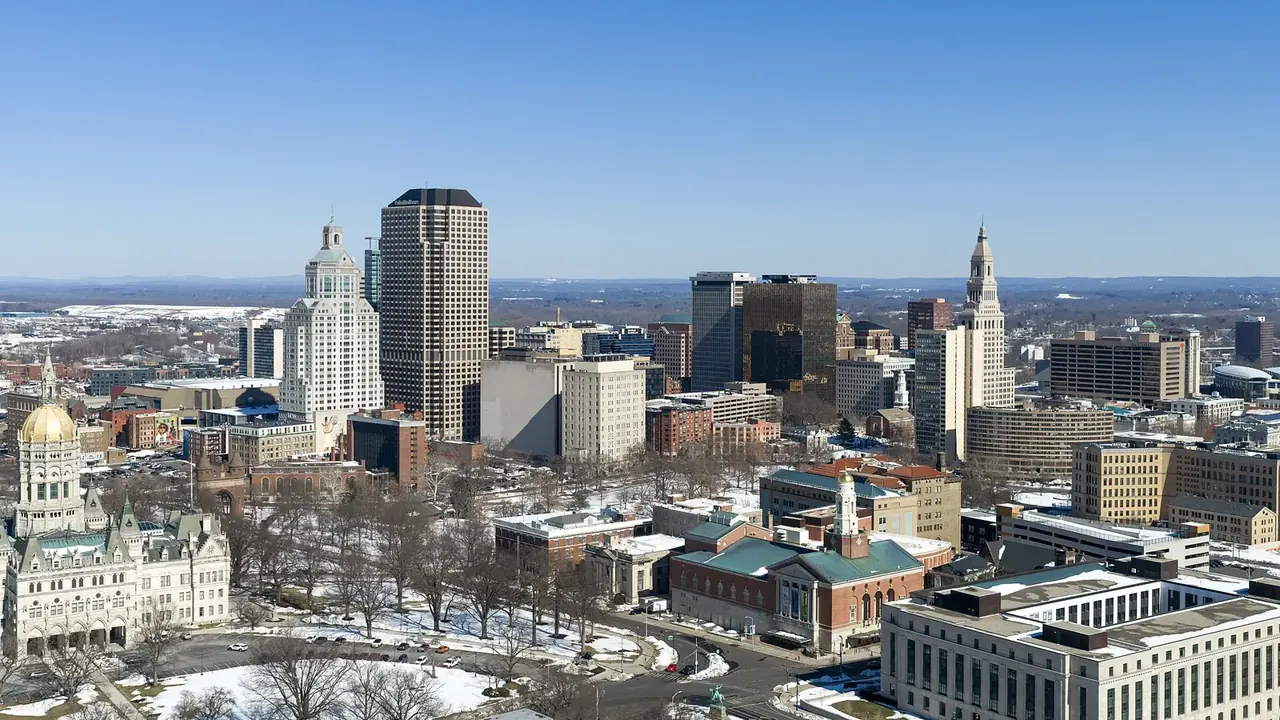
Hartford skyline

Photo: Quintin Soloviev, CC BY 4.0, via Wikimedia Commons.

The Local Numbers

Hartford Rental Market at a Glance

$203,792
Typical home value
+1.9% over 12 months
$1,600/mo
Typical rent
+2.9% over 12 months
9.4%
Annual rent to value
Typical rent x 12, divided by typical value

Source: Zillow Home Value Index (mid-tier single-family and condo) and Zillow Observed Rent Index for Hartford, August 2026. Figures are market-wide typical values, not an appraisal or a quote.

Local Rules

Investing in Hartford: The Local Rules

Rental registration and inspection

  • Hartford requires a four-year Rental License for each building with three or more units, except owner-occupied three-families, and the Fire Marshal inspects licensed buildings every year of the term.

    For investors: The license replaces the $25-per-unit Certificate of Apartment Occupancy for units in the building, and its fee covers only the first housing and fire code inspections. Buildings with five or more housing code violations can be pulled into the program ahead of schedule.

    Source: City of Hartford Development Services, Apply for a Rental License, Oct 2026

  • Non-owner-occupied Hartford three-unit buildings, the program's final phase, must apply between July 1 and October 31, 2026, at $60 plus $50 per unit; a late application adds a $1,000 penalty.

    For investors: A non-owner-occupied three-family bought this fall still has to be licensed by October 31, 2026, or the $1,000 late penalty applies, and renting unlicensed can bring daily per-unit fines. Four- to nine-unit buildings had their 2025 window, so ask the seller for that license.

    Source: City of Hartford Development Services, Apply for a Rental License, Oct 2026

Property tax

  • Hartford's tax office lists a FY2027 mill rate of 69.95 and says residential property is assessed at 36.75% of market value this year, against 70% everywhere else in Connecticut.

    For investors: The page ties the lower effective rate to single-family, two-family and three-family homes, so confirm with the Assessor before assuming a fourplex qualifies. Its posted 36.20 effective rate matches the prior 68.95 mill rate, so recompute rather than reuse it.

    Source: City of Hartford, Office of the Tax Collector, Oct 2026

  • Hartford assessments still rest on the October 1, 2021 revaluation, and the next citywide revaluation is set for the October 1, 2026 grand list.

    For investors: New values from this revaluation reach the bills due July 2027, so a deal underwritten on today's assessment can reprice in its first full year. Appeals go to the Board of Assessment Appeals, whose filing deadline this year was February 20.

    Source: City of Hartford, Office of the Tax Assessor, Oct 2026

  • Under code 9-98B, Hartford may defer all added assessment for five years on residential buildings at least 15 years old with two-plus blight violations and rehab spending of 30% or more of assessed value.

    For investors: File the deferral request with the Assessor at the same time as the building permit applications. The deferral then tapers to 80, 60, 40 and 20%, and a buyer who acquires an approved property before its certificate of occupancy must reapply before work restarts.

    Source: Hartford Municipal Code section 9-98B, Reduction in assessment for rehabilitated structures, Aug 2026

Tax calendar

  • Hartford bills property tax in July and January installments; the July 2026 installment went delinquent after August 3, 2026 at 1.5% interest a month, and the next tax sale is November 6, 2026.

    For investors: Confirm both installments are paid at closing, because a missed one runs 18% a year with a $2 minimum. A buyer closing in December should hold reserves for the January 1 installment, which turns delinquent after February 1.

    Source: City of Hartford, Office of the Tax Collector, Oct 2026

Rent control and eviction rules

  • Hartford's Fair Rent Commission, governed by Ordinance 15-19 of October 2019, has five mayoral appointees including at least two tenants and two landlords, and can cap rents it finds harsh and unconscionable.

    For investors: Development Services staff may first try to settle a complaint informally. The ordinance weighs taxes, overhead including debt service, repairs and reinvestment, so keep records tying each increase to costs; the commission can also order a landlord to stop retaliating against a complaining tenant.

    Source: Hartford Municipal Code, Chapter 2, Article V, Division 21, Fair Rent Commission, Aug 2026

Short-term rentals

  • Hartford zoning limits short-term room rentals to 21 cumulative days and three rentals per unit in any six months, requires a zoning permit first, and caps guests at four adults.

    For investors: An owner living in the unit can rent part of it with no day caps, and a special permit can allow more. Otherwise, outside the N-#-1 districts a manager within 10 miles may run it, except on single-unit lots, and permits expire within three years.

    Source: Hartford Zoning Regulations section 3.5.1.E, Room Rental - Short Term, Aug 2026

ADUs and lot splits

  • Hartford zoning allows one ADU only on a lot holding a single one-unit dwelling, capped at half the main home's floor area or 1,000 square feet, whichever is less, with no separate street address.

    For investors: That rules out adding an ADU behind an existing two- or three-family. The unit is limited to two adults plus related minor children, needs parking at the two-unit standard, and inside the main house cannot get a new utility connection unless the lot already has more than one.

    Source: Hartford Zoning Regulations section 3.5.1.A, Accessory Dwelling Unit, Aug 2026

Utilities

  • Hartford's Metropolitan District 2026 charges are $3.91 per ccf of water, a $4.87 per ccf Clean Water Project charge, and $28.23 in monthly fixed fees for a 5/8-inch meter.

    For investors: Sewer treatment in member towns like Hartford is mostly paid through the MDC ad valorem share of the property tax bill, so the water bill shows usage and fixed charges on top. Where one meter serves several units, the owner carries it all unless leases bill tenants back.

    Source: The Metropolitan District, Water and Sewer Rates effective January 1, 2026, Jan 2026

Flood zones

  • Hartford Public Works, whose duties include the city's flood control systems, lists a South Meadows (Clark) Dike repair project; the Army Corps notice proposes replacing 6,000 feet of toe drain on the Connecticut River levee.

    For investors: Low-lying blocks near the South Meadows rely on that levee, so pull the FEMA zone for the exact parcel and price flood coverage even where the map shows reduced risk. Hartford is not on FEMA's premium discount list, unlike neighboring West Hartford.

    Source: City of Hartford Department of Public Works, Levee Improvement Project and U.S. Army Corps of Engineers public notice, Oct 2026

What drives rental demand

  • Hartford Hospital, founded in 1854 as the city's first hospital, is an 867-bed regional referral center in the Hartford HealthCare network, and its divisions include the 114-bed Institute of Living.

    For investors: Connecticut Children's adds a 230-bed children's hospital on Washington Street, so hospital staff and trainees form a steady renter pool near both campuses. Furnished leases of a month or more avoid Hartford's short-term room rental limits.

    Source: Hartford Hospital, About Hartford Hospital, Oct 2026

Five-Year Trend

Hartford Home Values and Rents, Month by Month

Zillow typical values, Aug 2021 to Aug 2026. Tap a chart to read any month.

Typical home value $203,792 Aug 2026 +36.5% over 5 years
$141k $177k $212k 202120222023202420252026
Typical rent $1,600/mo Aug 2026 +38.4% over 5 years
$1,103 $1,378 $1,653 202120222023202420252026
DSCR Explorer

Would a typical Hartford rental cover its own payment?

Rent divided by the full monthly cost. Move the sliders.

1.00
estimated DSCR
Loan amount
Principal and interest
Taxes, insurance, dues
Total monthly cost
Estimated DSCR by loan-to-value
1.00
60%
1.00
65%
1.00
70%
1.00
75%
1.00
80%

Illustration only: 30-year amortizing payment, Zillow typical values (Aug 2026). Not an appraisal or a quote.

Beyond Single-Family

Small Multifamily Rentals in Hartford

Rental Housing by Building Size

Of 36,402 renter-occupied homes in Hartford:

  • 2 to 4 units13,744 (37.8%)
  • 5 to 9 units5,143 (14.1%)
  • 10 to 19 units3,657 (10.0%)

Median gross rent $1,221/mo · renters are 74% of households.

Source: U.S. Census Bureau, American Community Survey 5-year estimates (2019 to 2023), tables B25032, B25064 and B25003 for Hartford.

Investor Questions

Hartford Investor FAQ

Does a Hartford three-family I am buying need a rental license this year?

Yes, unless the owner lives in one unit. Non-owner-occupied three-unit buildings must apply between July 1 and October 31, 2026, at $60 plus $50 per unit for a four-year license, and late filers add a $1,000 penalty. The Fire Marshal then inspects every year.

Source: hartfordct.gov

Why is the effective tax on a Hartford two-family lower than the mill rate?

Hartford assesses residential property at 36.75% of market value this year, versus 70% elsewhere in Connecticut, and its tax page ties the lower effective rate to single-family, two-family and three-family homes. The FY2027 mill rate of 69.95 applies to that smaller base.

Source: hartfordct.gov

Can I host short-term guests in a Hartford rental?

Within zoning limits: a zoning permit first, at most 21 cumulative days and three rentals per unit in any six months, and four adults. An owner renting part of the unit they live in faces no day caps, and outside N-#-1 districts a manager within 10 miles can operate, except on single-unit lots.

Source: library.municode.com

Is there a Hartford tax break for rehabbing a blighted rental?

Yes. Under code section 9-98B, a residential building with two or more blight violations, at least 15 years old, rehabbed for at least 30% of assessed value, can defer the added assessment fully for five years, tapering to zero by year ten. Apply alongside the building permits.

Source: library.municode.com

Connecticut

Connecticut Rules Investors Ask About

Foreclosure

Connecticut foreclosures go through the courts, usually as a strict foreclosure that vests title in the lender, though the court may instead order a foreclosure sale.

Source: Connecticut General Statutes § 49-24, Oct 2026

Foreclosure

Connecticut's court foreclosure mediation program covers owner-occupied 1-4 family primary residences, so foreclosures on non-owner-occupied rentals are generally outside it.

Source: Connecticut General Statutes §§ 49-31k, 49-31l, Oct 2026

All Connecticut city guides ›

LiButti Capital

Get your personalized rate.

Tell us about the deal. No tax returns, and no credit pull to see where you stand.

📞 Call us now (650) 200-2304
8% complete · Loan type
⏱ About 30 seconds ✓ No credit pull to see your rate ✓ No tax returns — the property qualifies, not your paycheck

What kind of loan are you looking for?

Are you the investor, or a broker?

What are you looking to do?

Where are you in the purchase?

What type of property is it?

How will it be rented?

What's the monthly market rent?

Current or expected rent — a ballpark is fine.

Where's the property?

Start typing and pick from the suggestions.

Roughly, what are the numbers?

Ballpark is fine — this is what prices your rate.

Tell us about the project

Ballpark numbers are perfect.

Rentals you own plus flips or builds you have finished, 0 to 200.

What's your estimated credit score?

A ballpark is perfect — we do not pull your credit.

How much investing experience do you have?

✓ Based on what you shared, this looks like a deal we can price

Submit

Enter your details and an advisor calls you to walk through your rate and structure. Does that work for you?

✓ No credit pull to see your rate  ·  ✓ No tax returns  ·  ✓ Business-purpose only

⌂ LiButti Capital · NMLS #2682926 · Equal Housing Opportunity

Products shown are business-purpose investor loans (such as DSCR) secured by non-owner-occupied property. They are not consumer mortgages and are not intended for personal, family, or household use.

Estimates are based on the information you provide and assume it is accurate and complete. Actual terms depend on full underwriting, appraisal, title, and program eligibility and may differ. The rate shown is the note rate, not the APR; figures exclude taxes, insurance, and certain third-party costs. The payment shown is principal and interest, or interest only where an interest-only option was selected; interest-only payments do not reduce the loan balance and the payment increases when the interest-only period ends.

Compensation and fees vary by loan amount, program, and transaction and are finalized in your loan documents at closing. By submitting, you authorize LiButti Capital to contact you about your inquiry by phone, text, and email (which may be autodialed or prerecorded) and to obtain consumer/credit reports as needed; message and data rates may apply. See our Privacy Policy.

Coverage

States We Serve

DSCR loans in 40 states and Washington, D.C. Fix and flip, rehab, and ground-up construction in 40 states and Washington, D.C.

AL AK AZ AR CA CO CT DE DC FL GA HI ID IL IN IA KS KY LA ME MD MA MI MN MS MO MT NE NV NH NJ NM NY NC ND OH OK OR PA RI SC SD TN TX UT VT VA WA WV WI WY
DSCR And Rehab/Construction Not Currently Available