Client Portal
Glendale, California

Investment Property Loans in Glendale, CA

DSCR loans, plus fix and flip and ground-up construction financing, for investors buying or refinancing in Glendale and surrounding cities.

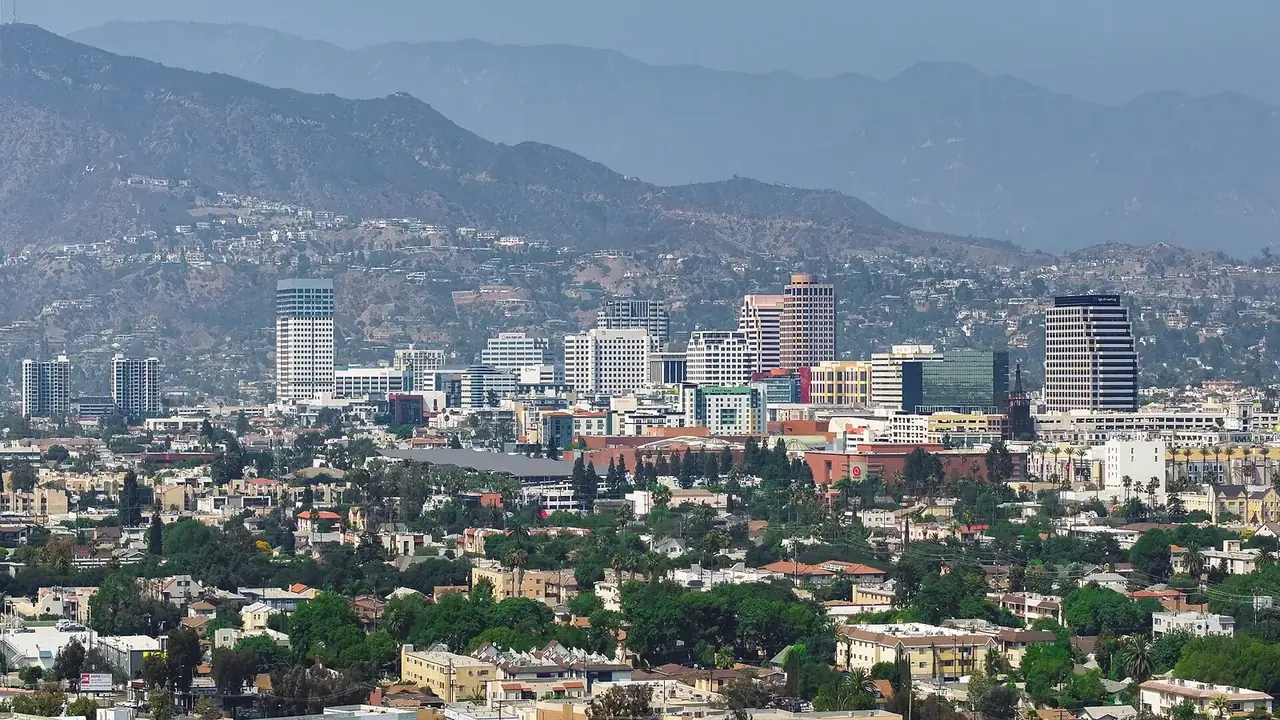
Glendale skyline

Photo: Quintin Soloviev, CC BY 4.0, via Wikimedia Commons.

The Local Numbers

Glendale Rental Market at a Glance

$1,180,773
Typical home value
+1.4% over 12 months
$2,790/mo
Typical rent
+0.2% over 12 months
2.8%
Annual rent to value
Typical rent x 12, divided by typical value

Source: Zillow Home Value Index (mid-tier single-family and condo) and Zillow Observed Rent Index for Glendale, August 2026. Figures are market-wide typical values, not an appraisal or a quote.

Local Rules

Investing in Glendale: The Local Rules

Landlord rules

  • Under Glendale's Rental Rights Program, a covered tenant who moves out after a rent increase above 7% within 12 months is owed relocation of three times the proposed new rent.

    For investors: On a $2,200 proposed rent that is $6,600, doubled to $13,200 for a qualified tenant. The landlord pays half within 5 days of the request and the rest within 5 days of move-out, so keep a Glendale increase at or under 7% unless banked room exists.

    Source: City of Glendale Rental Rights Program, Guide to Rent Increase Relocation Assistance, Oct 2026

  • Glendale landlords may bank unused room under the 7% threshold from the prior three years, up to 21% in total, apply at most 15% from the bank at once, and pass it to a buyer.

    For investors: A seller who held rents flat can pass usable bank to a Glendale buyer, though no increase may exceed the state cap. Ask for three years of rent ledgers and past notices during due diligence so the bank can be documented.

    Source: City of Glendale Rental Rights Program, Guide to Rent Increase Relocation Assistance (Banking), Oct 2026

  • Glendale's just-cause and rent-increase relocation rules exclude single-family homes, condos, townhouses and parcels with two or fewer units; rent-increase relocation also skips buildings with a certificate of occupancy after 1995.

    For investors: A Glendale house, condo or duplex sits outside these city rules, leaving state law. A pre-1995 triplex or larger falls inside them, so a buyer stepping up from two units to three should budget for relocation exposure on any increase above 7%.

    Source: City of Glendale Rental Rights Program, Frequently Asked Questions (Exemptions), Oct 2026

  • Glendale's right-to-lease rule covers parcels with five or more units: landlords must offer new tenants, and current tenants receiving a rent increase, a written one-year lease stating the rent for the full term.

    For investors: For a Glendale building of five or more units, put the lease offer in the same notice as the increase. Renewal offers on a fixed-term lease go out at least 60 days before it ends, and the tenant then has 30 days to decide.

    Source: City of Glendale Rental Rights Program, Right to Lease guide, Oct 2026

  • Glendale's 2024 update, in effect since March 7, 2024, sets no-fault eviction relocation at three times the greater of current rent or Fair Market Rent, plus $2,000, doubled for qualified tenants.

    For investors: With the city's 2026-27 two-bedroom Fair Market Rent of $2,903, a no-fault move-out in Glendale costs at least $10,709 per unit. Parcels of four or fewer units are spared relocation only for major rehabilitation evictions.

    Source: City of Glendale Rental Rights Program, Frequently Asked Questions and program guide, Oct 2026

Short-term rentals

  • Glendale allows only hosted home-sharing, where the host lives on site during the guest's stay, and prohibits vacation rentals with no host present, covering residential stays of 30 consecutive days or less.

    For investors: A Glendale purchase cannot run as a whole-home vacation rental, so price it on leases longer than 30 days. Owners who live on site can seek a home-sharing license through the city's GlendalePermits.org portal or the Licensing Office.

    Source: City of Glendale Licensing, Home-Sharing, Oct 2026

  • Glendale's finance department lists a 12% transient occupancy tax, which the operator collects from each guest with the room payment and remits to the city under Municipal Code Chapter 4.32.

    For investors: A resident host renting a spare room in Glendale must register for the tax, collect 12% of each stay's rent and remit it to the city. Build it into nightly pricing from the start, since guests compare all-in totals.

    Source: City of Glendale Finance, Transient Occupancy Tax, Oct 2026

Transfer tax

  • Glendale is absent from the Los Angeles County recorder's list of five cities that add their own transfer tax, so a Glendale deed pays only the county's $0.55 per $500 of value.

    For investors: On a $1.4 million Glendale triplex the transfer tax is about $1,540. The same price inside the City of Los Angeles would add $2.25 per $500, about $6,300 more, which matters when comparing listings along the border.

    Source: Los Angeles County Registrar-Recorder/County Clerk, Documentary Transfer Taxes, Oct 2026

Utilities

  • Glendale bought its electric utility in 1909, and Glendale Water and Power now serves more than 90,000 customers across a 31-square-mile area.

    For investors: Rental owners in Glendale open power and water accounts with the city utility rather than an investor-owned company. Check whether a building has separate electric meters, since owner-paid house meters billed by the city become a fixed operating cost.

    Source: Southern California Public Power Authority, Member: City of Glendale, Oct 2026

What drives rental demand

  • Adventist Health Glendale describes itself as a 515-bed tertiary care hospital and says it has served the community for more than a century.

    For investors: A hospital of that size runs around the clock, so nurses, technicians and residents look for rentals with short drives. Units near the medical campus can lease to clinical staff who weigh commute time over square footage.

    Source: Adventist Health Glendale, About Us, Oct 2026

  • Glendale Community College, formed after a 1926 vote of Glendale citizens, reported more than 25,000 students in 2018 across its Verdugo Campus, Garfield Campus and Montrose center.

    For investors: Students and faculty add steady demand for rooms and one-bedroom units near the Verdugo Campus. The enrollment figure dates from 2018, so check current numbers before leaning on student demand in a Glendale rent forecast.

    Source: Glendale Community College, About GCC, Oct 2026

Market note

  • Glendale's Housing Authority created GRASP in December 2025 to give renters hit by a destabilizing financial event temporary rent help; the first application window ran July 6 to 20, 2026.

    For investors: Applicants are ranked by urgency and the first window lasted two weeks, so GRASP is no sure fix for arrears. Still, nonpayment evictions and job loss are listed hardships, so a Glendale landlord can point a struggling tenant to the program.

    Source: City of Glendale, Glendale Rental Assistance and Stabilization Program (GRASP), Oct 2026

Five-Year Trend

Glendale Home Values and Rents, Month by Month

Zillow typical values, Aug 2021 to Aug 2026. Tap a chart to read any month.

Typical home value $1,180,773 Aug 2026 +19.0% over 5 years
$967k $1099k $1231k 202120222023202420252026
Typical rent $2,790/mo Aug 2026 +18.2% over 5 years
$2,304 $2,593 $2,882 202120222023202420252026
DSCR Explorer

Would a typical Glendale rental cover its own payment?

Rent divided by the full monthly cost. Move the sliders.

1.00
estimated DSCR
Loan amount
Principal and interest
Taxes, insurance, dues
Total monthly cost
Estimated DSCR by loan-to-value
1.00
60%
1.00
65%
1.00
70%
1.00
75%
1.00
80%

Illustration only: 30-year amortizing payment, Zillow typical values (Aug 2026). Not an appraisal or a quote.

Beyond Single-Family

Small Multifamily Rentals in Glendale

Rental Housing by Building Size

Of 47,379 renter-occupied homes in Glendale:

  • 2 to 4 units6,893 (14.5%)
  • 5 to 9 units9,692 (20.5%)
  • 10 to 19 units9,046 (19.1%)

Median gross rent $2,095/mo · renters are 65% of households.

Source: U.S. Census Bureau, American Community Survey 5-year estimates (2019 to 2023), tables B25032, B25064 and B25003 for Glendale.

Investor Questions

Glendale Investor FAQ

Does Glendale cap rent increases?

No city cap; state limits still apply. Glendale's Rental Rights Program instead requires relocation of three times the proposed rent when a covered tenant moves out after an increase above 7% within 12 months. Houses, condos, duplexes and post-1995 buildings are outside that rule.

Source: glendalerentalrights.com

Which Glendale rentals are exempt from the city's tenant rules?

Single-family homes, condos, townhouses and parcels with two or fewer units are outside just-cause and rent-increase relocation, and post-1995 buildings skip the rent-increase relocation. The right-to-lease rule exempts parcels with four or fewer units.

Source: glendalerentalrights.com

Can a Glendale property be listed as a vacation rental?

No. Glendale prohibits vacation rentals where no host lives on site. Only hosted home-sharing is allowed for stays of 30 days or less, and hosts need a city license and must collect the 12% transient occupancy tax.

Source: glendaleca.gov

Must Glendale landlords offer a one-year lease?

On parcels with five or more units, yes. Landlords must offer new tenants, and current tenants getting a rent increase, a written one-year lease with the rent stated. A tenant who does not answer a renewal offer in time is treated as declining it.

Source: glendalerentalrights.com

California

California Rules Investors Ask About

Security deposits

California landlords must return the deposit with an itemized statement within 21 days after move-out, and must photograph the unit at move-in for tenancies starting on or after July 1, 2025.

Source: California Civil Code § 1950.5(g)-(h), Oct 2026

Rent control

California's statewide cap holds rent increases to 5% plus inflation, never over 10%, per 12 months; newer buildings and noticed non-corporate single-family homes are exempt, and the law sunsets in 2030.

Source: California Civil Code § 1947.12 (AB 1482), Oct 2026

All California city guides ›

LiButti Capital

Get your personalized rate.

Tell us about the deal. No tax returns, and no credit pull to see where you stand.

📞 Call us now (650) 200-2304
8% complete · Loan type
⏱ About 30 seconds ✓ No credit pull to see your rate ✓ No tax returns — the property qualifies, not your paycheck

What kind of loan are you looking for?

Are you the investor, or a broker?

What are you looking to do?

Where are you in the purchase?

What type of property is it?

How will it be rented?

What's the monthly market rent?

Current or expected rent — a ballpark is fine.

Where's the property?

Start typing and pick from the suggestions.

Roughly, what are the numbers?

Ballpark is fine — this is what prices your rate.

Tell us about the project

Ballpark numbers are perfect.

Rentals you own plus flips or builds you have finished, 0 to 200.

What's your estimated credit score?

A ballpark is perfect — we do not pull your credit.

How much investing experience do you have?

✓ Based on what you shared, this looks like a deal we can price

Submit

Enter your details and an advisor calls you to walk through your rate and structure. Does that work for you?

✓ No credit pull to see your rate  ·  ✓ No tax returns  ·  ✓ Business-purpose only

⌂ LiButti Capital · NMLS #2682926 · Equal Housing Opportunity

Products shown are business-purpose investor loans (such as DSCR) secured by non-owner-occupied property. They are not consumer mortgages and are not intended for personal, family, or household use.

Estimates are based on the information you provide and assume it is accurate and complete. Actual terms depend on full underwriting, appraisal, title, and program eligibility and may differ. The rate shown is the note rate, not the APR; figures exclude taxes, insurance, and certain third-party costs. The payment shown is principal and interest, or interest only where an interest-only option was selected; interest-only payments do not reduce the loan balance and the payment increases when the interest-only period ends.

Compensation and fees vary by loan amount, program, and transaction and are finalized in your loan documents at closing. By submitting, you authorize LiButti Capital to contact you about your inquiry by phone, text, and email (which may be autodialed or prerecorded) and to obtain consumer/credit reports as needed; message and data rates may apply. See our Privacy Policy.

Coverage

States We Serve

DSCR loans in 40 states and Washington, D.C. Fix and flip, rehab, and ground-up construction in 40 states and Washington, D.C.

AL AK AZ AR CA CO CT DE DC FL GA HI ID IL IN IA KS KY LA ME MD MA MI MN MS MO MT NE NV NH NJ NM NY NC ND OH OK OR PA RI SC SD TN TX UT VT VA WA WV WI WY
DSCR And Rehab/Construction Not Currently Available